Get Started with a Quote Today!
Do you operate a staffing company? Are you in a cash crunch and unable to make payroll? We’ll help you find the best payroll funding provider.
Payroll funding, also called invoice factoring, is a form of financing specifically designed for the staffing industry. Many staffing companies must wait 30-90 days to collect payment on invoices, but need to make payroll far sooner. By selling your receivables for money up front, you can achieve steady cash flow and sustainable growth. Check out our online resources or contact us to find out more about finding the right provider for you.
Payroll funding is the act of selling your accounts receivable for cash up front. Also known as invoice factoring, it is a form of financing specifically designed to help staffing companies make payroll before they collect from their customers. When you submit an invoice to a customer, the payroll funding provider purchases that unpaid invoice from you and gives you the cash that day. Once your customer pays the invoice, the provider sends you the rest of the money, minus their fee.
Payroll funding essentially turns one asset (an invoice or receivable) into another (cash). In its simplest form:
In a typical relationship, there are three direct players and (in many cases) one indirect entity involved. They are:
*If the payroll funding provider is a bank itself, there is no need for a fourth participant or additional borrowing.
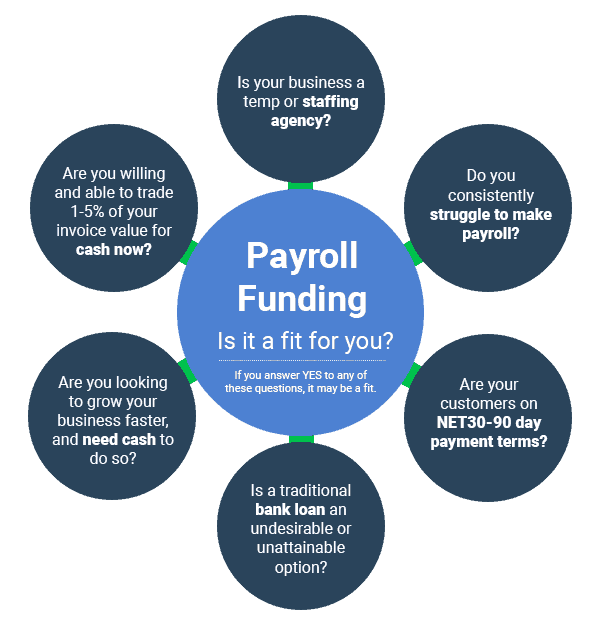
As a form of specialty financing, payroll funding may not be a fit for all businesses. In particular, staffing companies that have flat growth and long-established operating histories may prefer to tap either traditional forms of credit or to self-finance their working capital.
Typically, invoice factoring is utilized by small and mid-sized staffing firms (also known as staffing factoring) that are either experiencing one or all of the following:
Long-story short, if you’re a small or mid-sized staffing firm that would like to smooth out cash flow, invoice factoring is likely a solution.
How much does payroll funding cost?
There are typically two sources of costs when evaluating a relationship. The first source is the discount rate (think of this as interest rate) and the second is fees. Fees can vary wildly and may include transaction fees, lockbox fees, application fees, etc. If you see these fees in your agreement, move on and find a more straightforward funding provider.
In regards to discount rate, pricing can range from under 1% of the face value of an invoice to upwards of 5%. Rates are determined by the staffing company’s volume of business, the credit quality of its customers, and the length of time it typically takes for customers to pay.
As an example, the average staffing company billing $850,000 a year with customers paying in 31.3 days paid a discount rate of 2.76% on the face value of their invoice. So for a $10,000 invoice that was outstanding for 31.3 days, the staffing company was charged $276.
Get an in-depth look at the industry with and our latest pricing and benchmarking report.
What should I look for in a payroll funding solution?
First and foremost, you should look for someone you can trust. A good financing company can act as a catalyst for growth. A bad one…well, it can put your company in jeopardy.
On the surface, cost may seem to be the most important concern when evaluating partners. While cost should absolutely be considered, it’s how your payroll funding company interacts with your staffing company’s customers that should be the primary focus.
How are collections handled? What will your account team look like? Do they understand staffing? What’s their reputation? Do they also handle payroll processing?
By working with an established funding partner or an FDIC member bank that offers payroll funding, you’ll have more comfort in your partner’s ability to complement your business goals.
For more information about what to look for in a partner, access our guide to choosing a provider.
What will my customers think about a third-party getting involved in collections?
Payroll funding and other alternative financing platforms have been around for decades (and even centuries in some cases). As such, customers, their accounts payable departments, and their project managers are more than likely very familiar with payroll funding relationships.
As customers have moved towards stretching their suppliers’ payments out, customers’ familiarity with alternative financing companies has increased as the need for cash flow solutions has risen as well. Assuming you’ve got the right partner in place, most customers will see the financing relationship as only strengthening the financial viability of their own supply chains.
What do I need to get started for payroll funding?
Every factoring company has its own unique process for approval, but to get started, most just want to get a better understanding for your business, your customers, and what sort of financing line you may need.
Payrollfunding.com is not only a resource center, but we also help match staffing companies with a financing partner that fits their business needs.
Want to find out more about potential solutions? Get started with a quote today.
How quickly can I get started with payroll funding?
Once you’ve been approved for funding (sometimes within one business day) and you’ve submitted your unpaid invoices to the provider, you receive 80-90% of the invoice value immediately in cash. The remaining 10-20% is transferred to you once your customer pays their invoice, minus the provider’s fee. It’s that simple!
Can I have bad credit and still use payroll funding?
Yes. Unlike traditional bank loans, payroll funding approval is based primarily on the creditworthiness of your customers, not your own credit history. Since the financing company is essentially advancing you money against invoices your customers owe, they’re more concerned with whether your customers pay their bills on time than with your personal or business credit score. This makes payroll funding an accessible option for staffing companies that might not qualify for conventional financing due to limited credit history, past financial setbacks, or being too new to have established credit.
How do I find a reputable payroll funding company?
Look for a provider with specific experience in the staffing industry, since payroll funding for temp agencies has unique nuances (weekly payroll cycles, workers’ comp, multi-state payroll taxes) that generalist factoring companies may not handle well. Check references from other staffing agency owners, review the transparency of their fee structure, and ask how they handle customer communication during the collections process. A reputable provider will be upfront about all fees, won’t lock you into terms that don’t fit your business, and will be responsive when you need funds quickly. Payrollfunding.com can help match you with vetted partners suited to your specific needs.
What are typical contract terms for payroll funding?
Contract terms vary by provider, but most agreements run anywhere from month-to-month to one year, with some longer-term contracts offering lower rates in exchange for a commitment. Key terms to review include the advance rate (typically 80-90% of invoice value), the fee structure (often a percentage of the invoice that increases the longer it remains unpaid), minimum volume requirements, and any early termination penalties. It’s worth asking potential providers whether they offer month-to-month flexibility, since this can matter a lot if your funding needs fluctuate seasonally.
What if I don’t need payroll funding every month?
Many providers offer flexible, non-contractual arrangements that let you factor invoices only when you need to, rather than committing to fund your entire receivables portfolio every month. This is a good fit for staffing companies with seasonal fluctuations or occasional cash flow gaps rather than an ongoing need. That said, terms vary widely by provider, so ask directly about minimum volume requirements or usage fees before signing, as some companies do require a minimum monthly draw or charge a fee for inactive months.